
Free ETF IOPV API
Data, Fields & Validation
Find, evaluate, and integrate a free ETF IOPV API without confusing IOPV with official NAV, market price, holdings, or fund flows.
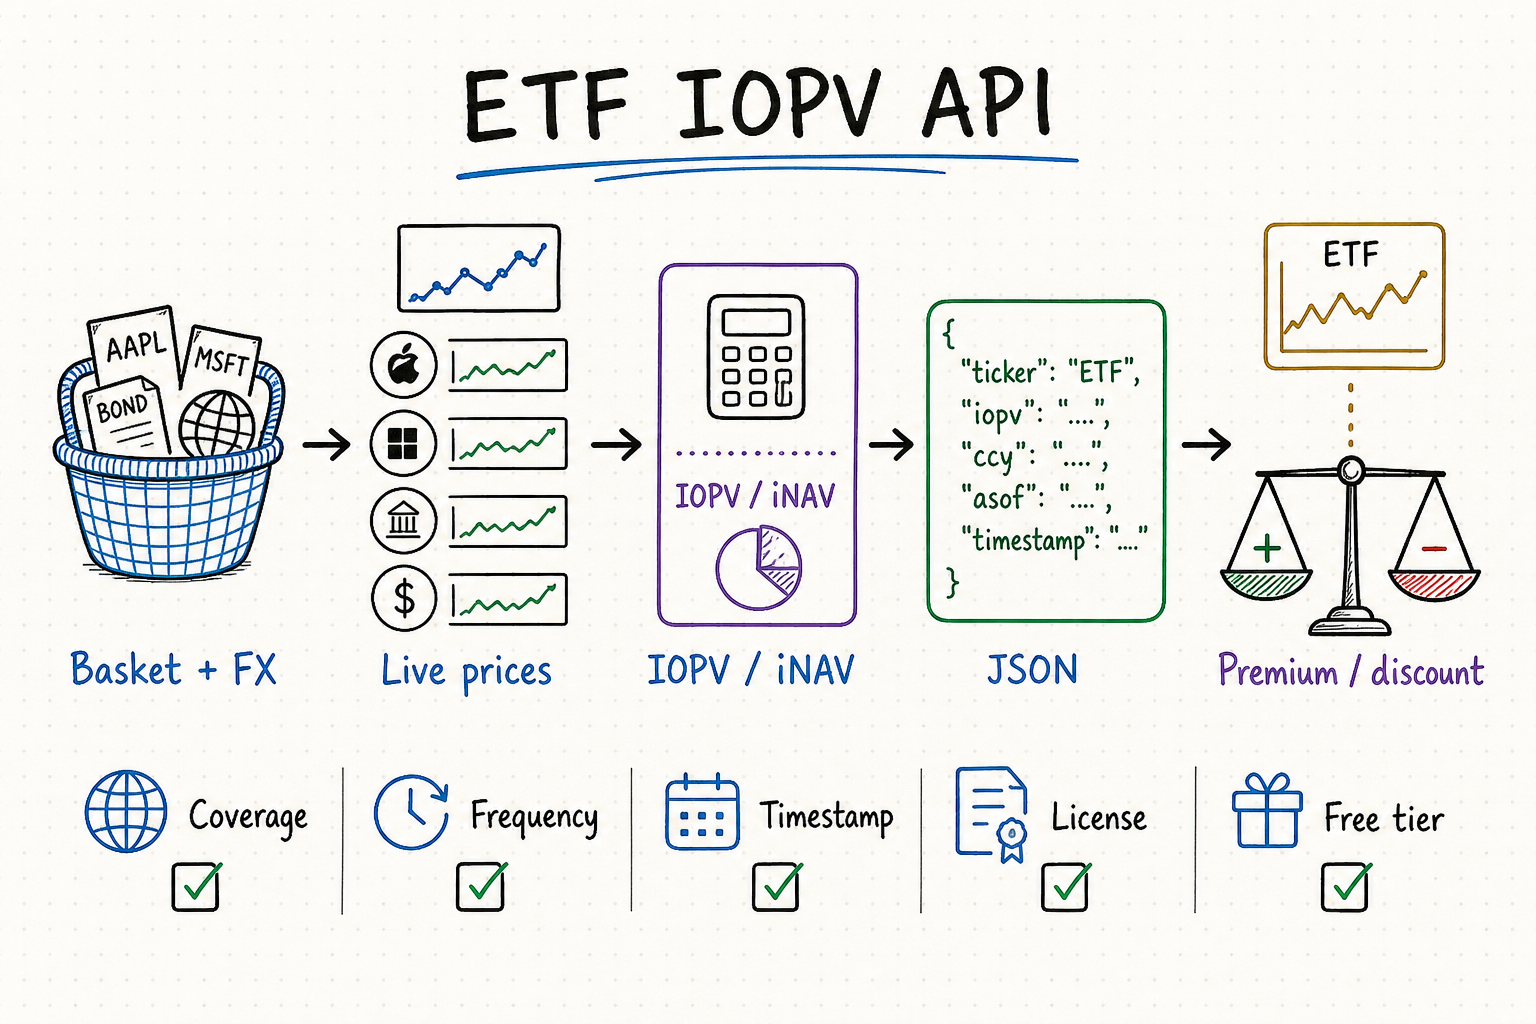
Free ETF IOPV API: what developers are looking for
A useful endpoint returns an ETF intraday indicative value plus enough metadata to decide whether that value is current and comparable. IOPV is also described as iNAV, IIV, intraday indicative value, or indicative optimized portfolio value. It is an estimate, not the fund’s final official NAV.
Its usefulness depends on the calculation inputs, not only the update interval. The basket may contain securities whose markets are closed, thin, halted, or priced through a proxy; foreign-currency assets require an FX observation; bonds and derivatives may rely on evaluated or modeled prices. A value refreshed every few seconds can still carry old economic information.
Find a documented indicative-value feed, understand its basket and pricing methodology, verify effective freshness, and test whether the license supports the intended display or analysis.
An ETF price, holdings, or daily NAV endpoint does not automatically provide IOPV—and an IOPV should not be presented as executable fair value or guaranteed arbitrage.
ETF indicative value API fields and related entities
| Field or entity | Why it matters | Validation question |
|---|---|---|
| symbol / exchange | Identifies the fund and listing venue. | Is the identifier exchange-qualified? |
| iopv / inav / iiv | Carries the intraday indicative estimate. | Is it truly IOPV rather than last price or NAV? |
| timestamp / asOf | Shows when the value was calculated or published. | What timezone and freshness guarantee apply? |
| currency / FX | Matters for cross-market baskets and conversions. | Which FX source and timestamp are used? |
| market price | Enables a premium or discount comparison. | Are price and IOPV timestamps aligned? |
| status / quality | Signals stale, halted, estimated, or unavailable data. | Can stale data be detected programmatically? |
| basket / methodology | Explains the positions, proxies, and calculation basis. | Does the feed disclose the basket date and methodology version? |
| component freshness | Shows whether underlying prices are open, closed, stale, or modeled. | Can the newest IOPV hide old component inputs? |
| calculatedAt / publishedAt / receivedAt | Separates computation, distribution, and ingestion delay. | Which time drives the freshness rule? |
How to evaluate a free ETF IOPV API
Confirm that the endpoint returns IOPV, iNAV, or IIV
Read the field definition. A generic ETF quote or daily net asset value is not a substitute for an intraday indicative value.
Check market coverage and calculation frequency
Verify supported exchanges and funds, trading-session behavior, delayed versus real-time status, update cadence, and treatment of foreign-market or closed components.
Inspect free-tier and licensing limits
Record authentication, request quotas, redistribution rights, attribution rules, commercial-use restrictions, and whether the “free” offer is a trial.
Validate timestamps and premium or discount logic
Compare aligned timestamps and currencies. Treat a large gap as a signal to investigate stale components, FX, trading halts, or methodology—not as guaranteed arbitrage.
Inspect basket and proxy-price methodology
Determine whether the calculation uses the current creation basket, last disclosed holdings, cash substitutions, evaluated bond prices, futures, ADRs, or other proxies. Record the basket date and methodology version with every observation.
Measure effective rather than headline freshness
Track value calculation, publication, receipt, market-price, FX, and component timestamps separately. The oldest material input can be more relevant than the newest top-level IOPV timestamp.
Validate ETF IOPV with aligned prices and explicit quality rules
Worked premium or discount example
Assume an ETF has a bid of 49.96, an ask of 50.04, and an IOPV of 49.90 at the same observation time. The midpoint is 50.00, so the indicative premium is (50.00 ÷ 49.90 − 1) × 100 ≈ 0.20%. The calculation should retain the bid, ask, IOPV, currency, venue, and all timestamps—not just the resulting percentage.
That 0.20% is not automatically executable. A market buy occurs near the ask, a sale near the bid, and both sides may move before an order arrives. If the IOPV is 45 seconds old while the quote is current, or if a material component is halted, label the result stale or incomparable instead of presenting it as a live arbitrage spread.
Cross-market example: a fresh timestamp can still contain stale economics
Consider a US-listed ETF holding Japanese equities. During the US session, Tokyo may already be closed. The distributor can refresh IOPV every few seconds by applying a current USD/JPY rate to Japanese closing prices, yet those equity prices do not reflect news released after the Tokyo close. Futures, ADRs, or statistical proxies may improve the estimate, but they also change its methodology and uncertainty.
Where an IOPV feed can come from
| Source route | What it can establish | Main limitation |
|---|---|---|
| Exchange or fund documentation | Official symbol, definition, dissemination code, cadence, and methodology notes | Documentation may not provide a freely callable real-time endpoint |
| Licensed market-data vendor | Normalized coverage, timestamps, status flags, and operational delivery | Real-time display and redistribution commonly require contracts or fees |
| General ETF quote API | Last trade, bid, ask, volume, and sometimes daily NAV | Those fields do not prove that an intraday indicative value is present |
Turn quality metadata into display and rejection rules
Fund, venue, currency, session, and timestamps align; the observation is within the configured age; no material component or FX warnings are present.
The value is delayed, the underlying market is closed, proxies are in use, or a small portion of the basket is stale—but the methodology and limitation are known.
The field definition is ambiguous, currency or listing differs, timestamps cannot be aligned, a material component is halted, or quality status is missing during a stressed market.
Integrate real-time ETF IOPV data safely
Step 1: inspect the API schema
Discover the operation and confirm required inputs, authentication, response fields, units, nullable values, error codes, and examples before sending production traffic.
Step 2: normalize the response
Map provider-specific names into a stable internal model such as symbol, venue, indicativeValue, currency, calculatedAt, receivedAt, delaySeconds, and qualityStatus.
Step 3: reject stale or incomparable values
Set freshness thresholds by venue, preserve the raw timestamp, align FX and market-price times, and surface missing or halted components instead of silently filling them.
Step 4: calculate a qualified premium or discount
Use an aligned bid, ask, midpoint, or trade price and label the choice. Confirm listing, share class, currency, and session, then attach time gaps and quality flags to the percentage instead of returning a bare number.
Step 5: test stressed and cross-market cases
Sample foreign-market closes, local holidays, component halts, fast FX moves, wide ETF spreads, bond funds, commodity products, and stale baskets. Verify that the integration degrades to “unreliable” rather than manufacturing precision.
Step 6: retain evidence and monitor drift
Store the raw response, calculation and receipt times, methodology, basket date, component-quality summary, FX source, market-price snapshot, and license state. Alert on schema changes, cadence gaps, or a persistent divergence from official NAV.
Use QVeris to find and call ETF IOPV capabilities
QVeris can help an agent discover relevant financial-data capabilities, inspect their schemas, and call an available operation through a consistent workflow. Availability, coverage, pricing, licensing, and data quality remain properties of the selected provider and must be verified before use.
- Require the exact indicative-value type, exchange-qualified fund ID, currency, session, maximum age, and quality fields in the capability request.
- Inspect whether the provider exposes basket date, methodology, component freshness, FX source, and separate calculation and receipt times.
- Route stale, halted, cross-market, or methodologically incomparable observations to review instead of converting them into trading instructions.
Free ETF IOPV API FAQ
Is there a free ETF IOPV API?
Some providers may offer trials or limited free access, but real-time exchange-derived indicative values often carry coverage, licensing, or redistribution restrictions. Verify the current plan and field definition.
What is ETF IOPV?
IOPV is an intraday estimate of an ETF’s value based on its basket and current component prices. It is not the official end-of-day NAV and may not equal the traded price.
Is IOPV the same as iNAV or IIV?
The terms often refer to closely related intraday indicative values, but providers and exchanges can use different methodologies and labels. Check the documentation.
How often is ETF IOPV updated?
The cadence depends on the venue and provider. Never infer it from the word “real-time”; inspect the documented frequency and timestamps returned by the endpoint.
Can IOPV be used as an executable fair value?
Not by itself. It is an indicative calculation whose inputs may be stale, modeled, closed, or incomplete. Trading decisions also require current bid, ask, depth, spread, session, and an understanding of the methodology.
Why does IOPV become less reliable for international ETFs?
Underlying markets may be closed while the ETF and FX continue trading. Proxy prices or stale closes can therefore make the estimate lag new information even when the top-level value refreshes frequently.
What timestamps should an IOPV API return?
At minimum, calculation and provider publication times; ideally receipt time, market-price time, FX time, basket date, and a summary of component freshness. One generic timestamp hides important latency.