
No survivorship shortcut
Use the historical universe that actually existed on the as-of date.
Turn a stock shortlist into an auditable pipeline with fixed inputs, factor rules, and evidence.
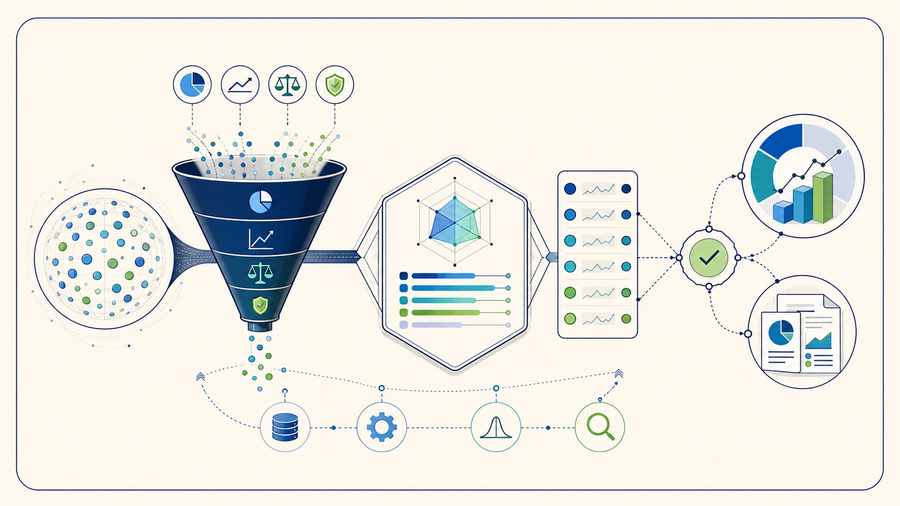
Convert a defined, investable universe into a smaller research list using rules that can be rerun with the same data and date.
Combine economically distinct value, quality, growth, momentum, risk, and liquidity signals instead of stacking several versions of one idea.
Show raw values, normalized scores, exclusions, sector exposure, and the reason each candidate passed—not only a mysterious composite rank.
Check point-in-time definitions, filing availability, outliers, missing values, rebalancing turnover, and transaction-cost sensitivity.
Fix market, security type, liquidity, and as-of date.
Collect value, quality, growth, momentum, risk, and liquidity inputs.
Winsorize, rank, or z-score with a declared peer group.
Apply weights and missing-value policy without silent substitutions.
Return raw inputs, scores, exclusions, and source timestamps.
A ranking is defensible only when the universe, as-of date, factor definitions, normalization, weights, exclusions, and source revisions are stored with the result.
| Factor | Example inputs | Common trap |
|---|---|---|
| Value | Earnings yield, book-to-price, FCF yield | Mixing negative and positive denominators |
| Quality | ROIC, margins, accruals, leverage | Using incomparable fiscal periods |
| Growth | Revenue and EPS growth | Ignoring base effects and acquisitions |
| Momentum | 6–12 month return, revisions | Look-ahead and stale prices |
| Risk | Volatility, beta, drawdown | Changing windows between names |
| Liquidity | Dollar volume, spread, turnover | Using average volume without price context |
A multi-factor stock screener is useful when each rule has a clear purpose. Value asks what you pay, quality examines business strength, growth measures change, momentum captures price behavior, while risk and liquidity test whether a candidate is practical to research. MSCI’s factor investing overview identifies value, quality, momentum, size, yield, and low volatility as established factor categories.
Raw factor values are rarely comparable across the whole market. Banks, software companies, utilities, and early-stage firms have different accounting structures and distributions. A credible screen states whether it ranks within sector or industry, how it winsorizes extreme values, whether it converts values to percentiles or z-scores, and how it combines scores when one input is missing.
Compare P/E, price-to-book, free-cash-flow yield, profitability, leverage, and cash-flow consistency. Definitions and sector norms matter.
Use revenue or earnings growth with price momentum over a stated lookback. Avoid treating recent performance as a forecast.
Market capitalization, trading volume, volatility, drawdown, and leverage can prevent an attractive score from hiding practical constraints.
Hard filters exclude stocks at a threshold; percentile ranks preserve more candidates and make cross-factor trade-offs easier to inspect.
Winsorize or cap extreme observations before ranking, then compare percentile or z-score behavior. Sector-relative ranks can reduce structural industry bets, but the chosen grouping and minimum group size must be explicit.
Measure correlation between signals and how often candidates change. A slightly stronger paper score may be less useful if it creates high turnover, wide-spread trades, or repeated exposure to the same underlying factor.
Use the historical universe that actually existed on the as-of date.
Apply filing availability dates, not only fiscal-period labels.
Expose null policy and the count of missing inputs.
Report why names entered or left the shortlist.
| Check | What to verify | Why it matters | Warning sign |
|---|---|---|---|
| Market coverage | Exchanges, security types, active and delisted stocks. | The starting universe changes every result. | Coverage is not disclosed. |
| Factor definitions | Formula, reporting period, units, and missing-value handling. | Similar labels may use different calculations. | Opaque scores without methodology. |
| Data freshness | Price delay, filing update time, and refresh schedule. | Stale inputs can alter a shortlist. | No timestamp or source. |
| Free-tier limits | Filters, exports, saved screens, alerts, and result caps. | “Free” may describe only a trial or partial workflow. | Paywall appears after rules are entered. |
| Normalization | Outlier cap, percentile or z-score, sector grouping. | Raw units and sector structures are not comparable. | A single outlier dominates the score. |
| Point-in-time data | Filing availability, restatements, old universes, delistings. | Controls look-ahead and survivorship bias. | Only today's values are available. |
| Portfolio realism | Turnover, capacity, spread, rebalance frequency, concentration. | A screen must survive implementation costs. | Only backtested return is shown. |
Choose market, exchange, security type, minimum size, and minimum liquidity before selecting factors. This prevents accidental comparisons across unlike securities.
Start with one or two rules from value, quality, growth, and momentum. Highly correlated filters can create false confidence without adding information.
Compare factor values, sector concentration, missing data, outliers, and the reason each stock passed. Save the exact rules and date.
Read current company filings and confirm recent figures before making any decision. Check the issuer, reporting period, units, restatements, and source timestamp.
Apply documented outlier handling, rank within the intended peer group, and combine factors with explicit weights. Preserve every raw value, transformed score, missing-value decision, and exclusion reason.
Shift thresholds, lookbacks, and rebalance dates slightly. Compare candidate overlap, sector weights, turnover, spreads, and performance after conservative costs; a robust research screen should not collapse after a tiny parameter change.
Store the eligible universe, source dates, filing availability, factor formulas, code version, ranking, and rejected rows. Rebuilding the screen later should reproduce the same list without consulting data published afterward.
Suppose Stock A is ranked only against eligible companies in its industry. After clipping each factor at documented cross-sectional limits and orienting every score so “higher is better,” it has value z = 1.2, quality z = 0.6, low-volatility z = 0.4, and no valid momentum observation. With target weights of 30% value, 30% quality, 25% momentum, and 15% low volatility, do not turn missing momentum into zero. Reweight the three available factors: (0.30×1.2 + 0.30×0.6 + 0.15×0.4) ÷ 0.75 = 0.80. Return the 0.80 composite together with the missing-factor flag, original 75% weight coverage, peer group, raw values, clipping limits, and as-of time.
Translate rank quality into implementable results. If a rebalance replaces 35% of portfolio notional and the conservative one-way cost is 20 basis points per traded dollar, the immediate cost estimate is 0.35 × 20 bp = 7 bp per rebalance, before taxes or market impact. Report gross and net results, turnover, spread assumptions, and capacity together. Historical tests must also retain securities that later delisted, use fundamentals only after their real publication time, and apply splits, dividends, symbol changes, and other corporate actions without rewriting the past universe.
Use QVeris to inspect candidate market and fundamental-data capabilities before they feed a ranking model. Continue with FMP provider details, then confirm the calling contract in the QVeris REST API reference.
It applies measurable rules to a defined stock universe and returns a smaller list for further research.
Some tools offer free multi-factor filters, but market coverage, delayed data, exports, saved screens, and advanced factors may be limited.
Start with a small, explainable mix such as valuation, profitability, growth, momentum, leverage, and liquidity. Learn each definition before combining rules.
No. It narrows a universe. Verify filings, data freshness, risks, valuation context, and personal suitability independently.
Not automatically. Accounting and valuation distributions differ by industry. Compare whole-market and sector-relative ranks, disclose the grouping method, and inspect whether neutrality removes information you intended to keep.
Use a documented rule: cap or winsorize plausible extremes, quarantine calculation errors, and distinguish not applicable from unavailable. Never convert every missing value to zero without testing the economic meaning.
Look-ahead bias, survivorship bias, crowded exposures, unstable thresholds, high turnover, poor liquidity, and ignored costs can turn an attractive historical shortlist into an unusable workflow.