
Free Index Data API
Sources, Limits & Python
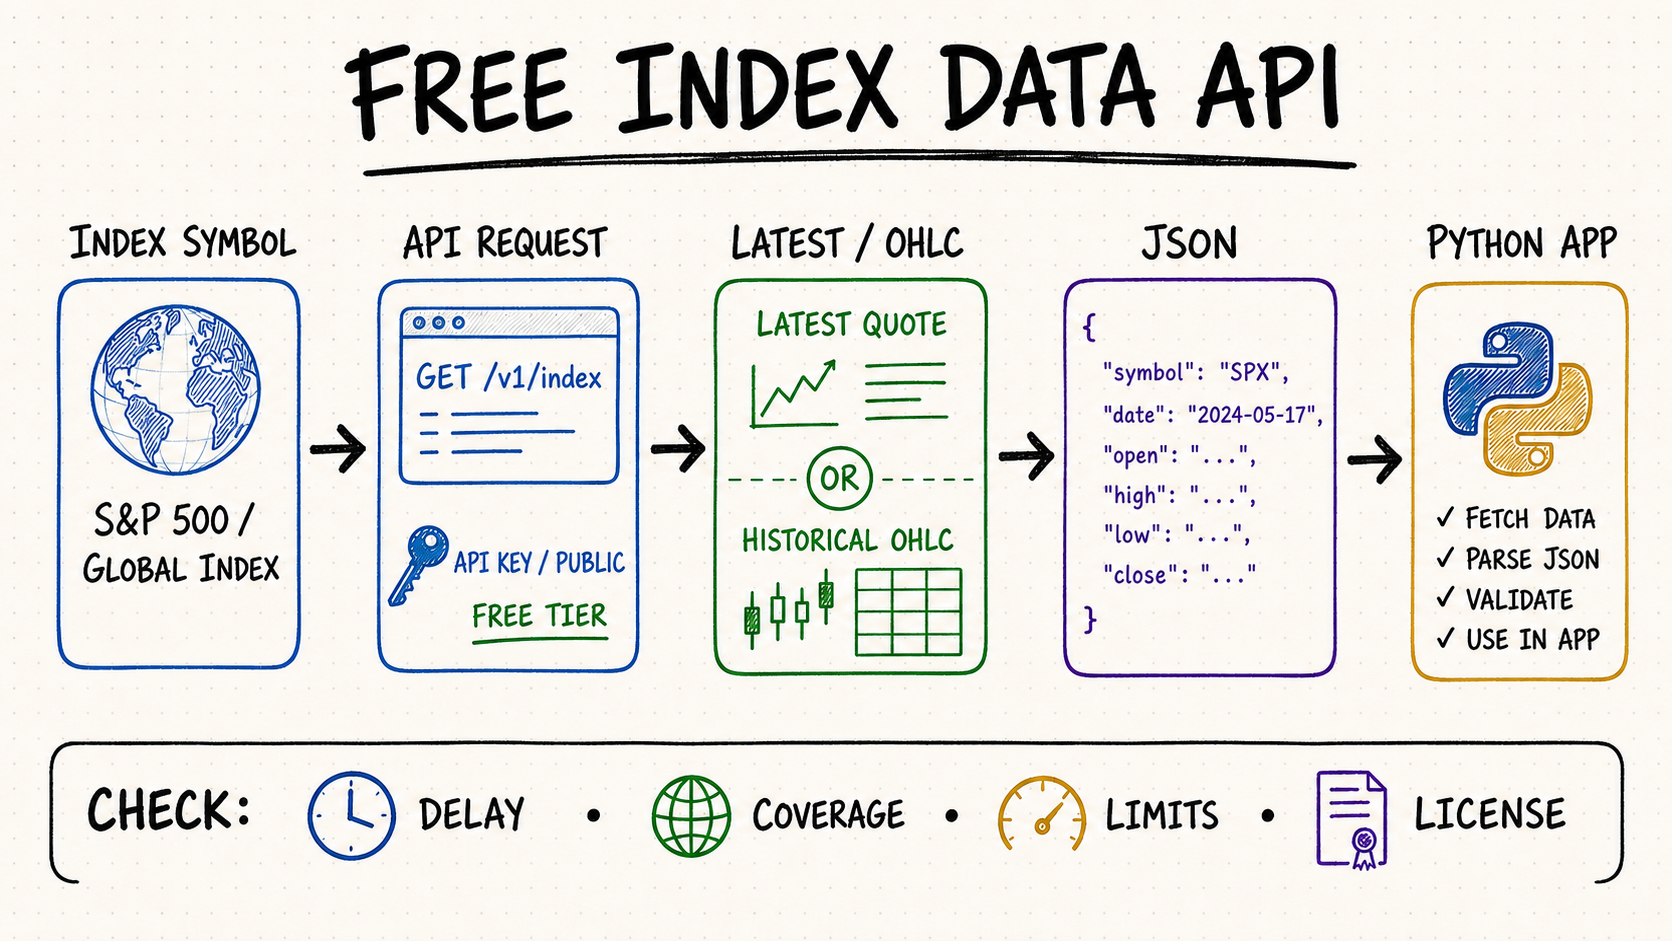
Compare free index data API sources for current quotes and historical OHLC, then test a documented JSON request before connecting it to your application.
Define the exact index series before choosing an API
The request must identify the exact index family, version, currency, and return convention. A price index, gross total-return index, net total-return index, hedged version, and real-time calculated variant can share a familiar name while producing different levels and histories. Store the publisher's stable identifier and methodology version, not only a display symbol.
A practical integration usually starts with a documented S&P 500 or global index identifier, then retrieves a latest level or historical OHLC series in consistent JSON or CSV for a dashboard, research notebook, or agent. The endpoint must expose enough reference metadata to prove that the requested and returned series are the same index variant.
Important: “Free” can mean a trial, delayed data, end-of-day access, a request-capped tier, or personal-use licensing. Confirm the current plan and timestamp before production use.
Coverage a stock index data API should provide
Latest market index quotes and timestamps
Check the index symbol, value, currency, exchange or publisher, observation time, timezone, and whether the quote is real-time, delayed, or end-of-day.
Free historical index data API
For charts and research, verify daily or intraday OHLC fields, start date, interval, missing sessions, adjustment rules, and maximum rows per request.
Global indices API coverage
Confirm that the plan includes the exact benchmarks and regions you need. A provider can advertise thousands of indices while restricting free access to a small subset.
JSON, API keys, rate limits, and licensing
Check authentication, calls per minute or day, response schema, error codes, caching, attribution, redistribution, and commercial-use rules.
Price, gross, net, and hedged index variants
Confirm treatment of dividends, withholding tax, FX, hedging costs, base currency, calculation calendar, inception date, and backfilled history. Values from different variants are not interchangeable.
Constituents, weights, and rebalance events
Require stable security IDs, weight basis, announcement and effective dates, additions, deletions, corporate-action adjustments, and historical snapshots. Today's member list cannot reconstruct a past index.
Official close, intraday level, and calculation status
Preserve observation time, publication time, session, status, and whether the value is official, preliminary, indicative, stale, or corrected. A fast response can still carry a delayed or stopped index calculation.
Free market index API sources to evaluate
Use a fixed benchmark set rather than a single famous symbol: one domestic equity price index, its total-return sibling, an international index, a currency-converted or hedged version, and one rebalance date. Compare identifiers, level and OHLC definitions, calendars, return treatment, delay, status, revision, constituent availability, and license.
Use the table as a verification checklist rather than an endorsement. Endpoint access, symbol coverage, delay, and licensing can change, so confirm every required series against the provider's current documentation and a known observation date.
| Source | Useful signal | Verify before use |
|---|---|---|
| Alpha Vantage | Official documentation lists index-data endpoints with daily, weekly, and monthly history in JSON or CSV. | Free-key quota, premium-marked symbols, delay, and commercial terms. |
| Massive | Its indices documentation describes reference, snapshot, historical, REST, WebSocket, and flat-file access. | What the current free Basic plan includes, market delay, and redistribution rights. |
| Financial Modeling Prep | Documents index quotes, index lists, and historical chart endpoints with a free-plan entry point. | Endpoint availability by plan, request quota, symbol coverage, and timestamp. |
| iTick | Markets REST and WebSocket access for real-time and historical indices with a limited personal free tier. | Time-limited wording, calls per minute, exchange coverage, and usage restrictions. |
Validate index returns, rebalances, and corporate actions
Worked return example: price and total-return indices answer different questions
Assume a price index starts at 1,000 and finishes the year at 1,080. Its price return is 8%. If constituent distributions add 25 index points when reinvested under the methodology, a comparable gross total-return index would end near 1,105, or 10.5% above the start. A net total-return version may finish lower after its stated withholding-tax assumptions.
The levels are illustrative, but the rule is operational: never splice a price series to a total-return series, and never infer dividend income by subtracting two indices unless publisher, base date, currency, calendar, tax convention, and methodology are compatible. Store the exact series identifier with every observation.
Worked rebalance timeline: announcement is not effective membership
Suppose a provider announces an addition on June 5, determines reference weights using June 14 data, publishes final weights on June 19, and makes the change effective after the June 21 close. A point-in-time constituent query for June 10 should keep the old membership while separately exposing the pending announcement. A portfolio tracking the index normally applies the new membership at the methodology's stated effective moment—not retroactively on June 5.
Keep announcement, reference, publication, implementation, and first-trading dates as separate fields. Historical research should use the information available by the simulated decision time and include deletions, suspended securities, and identifier changes. Using today's constituent list for earlier dates creates both look-ahead and survivorship bias.
Corporate actions can preserve economics while changing raw fields
Share count and price change mechanically. The index divisor or adjustment factor should preserve continuity; raw constituent prices cannot be compared without adjustment.
Price, total-return, and corporate-action treatment may differ. Preserve event type, ex-date, cash or distributed security, and methodology decision.
The economic position may continue under a new identifier, exchange, or share class. Map source IDs with effective dates instead of treating the old row as a loss and the new row as an unrelated addition.
Local-currency, converted, and hedged series use different FX observations and calendars. An equity move and a currency move must remain distinguishable.
Index data API Python example and validation
Normalize the provider response first, then validate the exact series identity together with its values. This example rejects a response that silently changes publisher, index variant, currency, or return treatment even when the display symbol looks unchanged.
from datetime import datetime
from decimal import Decimal, InvalidOperation


def parse_time(value: str) -> datetime:
    parsed = datetime.fromisoformat(value.replace("Z", "+00:00"))
    if parsed.tzinfo is None:
        raise ValueError("index timestamp must include a timezone")
    return parsed


def validate_index_history(payload: dict, expected: dict) -> list[dict]:
    identity = ("publisher", "index_id", "variant", "currency", "return_type")
    mismatched = [key for key in identity if payload.get(key) != expected.get(key)]
    if mismatched:
        raise ValueError(f"unexpected index series: {mismatched}")
    if payload.get("status") not in {"official", "corrected"}:
        raise ValueError("history is not an official or corrected series")

    rows = []
    previous_time = None
    for raw in payload.get("values", []):
        timestamp = parse_time(raw["timestamp"])
        try:
            opening = Decimal(str(raw["open"]))
            high = Decimal(str(raw["high"]))
            low = Decimal(str(raw["low"]))
            close = Decimal(str(raw["close"]))
        except (KeyError, InvalidOperation) as exc:
            raise ValueError("invalid index OHLC row") from exc
        if min(opening, high, low, close) <= 0:
            raise ValueError("index levels must be positive")
        if high < max(opening, close) or low > min(opening, close) or high < low:
            raise ValueError(f"impossible OHLC at {timestamp.isoformat()}")
        if previous_time is not None and timestamp <= previous_time:
            raise ValueError("index history must be strictly increasing")
        rows.append({"timestamp": timestamp, "open": opening,
                     "high": high, "low": low, "close": close})
        previous_time = timestamp
    if not rows:
        raise ValueError("response contains no index observations")
    return rows
Validate identity on every page of history. A provider can paginate or remap symbols independently. Recheck the five identity fields after each request and store them beside every observation; validating only the first page cannot prove that a long backfill remained on the same price, gross-return, net-return, or hedged series.
1. Choose a documented S&P 500 index symbol
Use the provider’s own identifier and endpoint. Keep the key server-side and send a request such as requests.get(url, params={"symbol":"SPX","interval":"daily"}, headers={"Authorization":f"Bearer {api_key}"}, timeout=20).
2. Validate HTTP and financial fields
Call raise_for_status(), parse JSON, and check symbol, timestamp, timezone, numeric open/high/low/close fields, nulls, sorting, and error messages. HTTP 200 alone does not prove useful data.
3. Respect free-tier limits and cache safely
Read rate-limit headers when available, back off on 429 responses, cache data according to the license, and record provider, endpoint, retrieval time, and source timestamp.
4. Compare delay, coverage, and license
Test a known session and several target indices. Confirm whether values are real-time, delayed, or end-of-day and whether display, analysis, and redistribution are permitted.
5. Resolve the index variant before joining history
Store publisher, family, version, currency, return type, hedging, and provider ID. Reject a symbol mapping that silently switches between price and total-return series or between local and converted currencies.
6. Validate rebalance and corporate-action dates
Rebuild several constituent changes with announcement, reference, and effective dates. Confirm weight units, closing or opening implementation, ticker changes, spin-offs, mergers, special dividends, and divisor or adjustment treatment.
7. Preserve point-in-time and revision evidence
Keep raw levels, constituent snapshots, publisher timestamps, first publication, correction IDs, methodology version, retrieval time, and entitlement. Historical research must use only data and membership known at the simulated time.
How QVeris helps connect index data capabilities
- Search separately for index levels, historical series, constituents, weights, and methodology or reference data.
- Require publisher, exact index variant, currency, return treatment, interval, date range, freshness, status, and entitlement in the capability request.
- Preserve provider IDs, source timestamps, revision state, methodology version, and license with every downstream result.
QVeris does not publish index values, grant market-data licenses, or guarantee a provider’s feed. It helps developers and agents discover available financial-data capabilities, inspect interfaces, and connect the selected external tool through a consistent workflow.
- Open the QVeris provider details for relevant financial-data capabilities.
- Inspect inputs, outputs, authentication, provider documentation, and supported index identifiers before connecting.
- Keep provider, effective date, retrieval time, and license notes with each result; QVeris connectivity is not investment advice.
Free index data API FAQ
Is there a free API for stock index data?
Yes. Some providers offer limited free tiers for delayed quotes or historical series. Verify exact index coverage, quota, timestamps, and licensing.
Which API provides historical index data?
Alpha Vantage, Massive, FMP, and other market-data providers document index history. Compare OHLC depth, intervals, free access, and formats.
Can I get real-time index data for free?
Sometimes for selected indices or personal use, but free plans are often delayed or end-of-day. Read the timestamp and entitlement notes.
How do I get S&P 500 index data via API?
Use the provider’s documented identifier, call its latest or historical endpoint, and validate timestamps, OHLC fields, limits, and license.
Do free index APIs require an API key?
Many do; some public endpoints do not. Keep credentials server-side and handle authorization and rate-limit errors explicitly.
What is the difference between a price and total-return index?
A price index generally excludes reinvested distributions, while a total-return version includes them under a stated gross or net tax convention. Their levels and performance cannot be compared without the variant label.
Can today's index constituents be used for a historical backtest?
No. Membership and weights change. Use point-in-time constituent snapshots with announcement and effective dates, including deleted securities, to avoid look-ahead and survivorship bias.
Why do two index APIs show different values?
They may map to different variants, currencies, observation times, official versus indicative states, calendars, corrections, or licensing delays. Compare publisher IDs and methodology before judging the number.